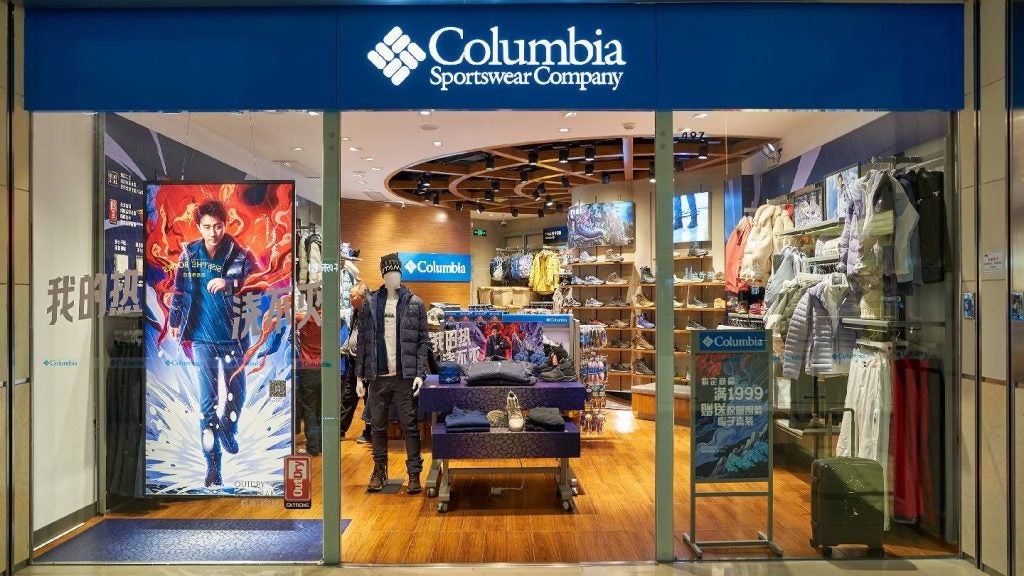
Columbia Sportswear now expects net sales for FY26 to be between $3.46bn and $3.50bn, up from a prior minimum of $3.43bn.
Diluted earnings per share are now projected between $4.65 and $4.90, up from the previous lower bound of $4.45, the firm stated.
Columbia maintained expectations for gross margin expansion, projecting it will reach between 52.1% and 52.3% of net sales for the year, supported by tariff refunds under the International Emergency Economic Powers Act (IEEPA).
The update follows Q3 net sales of $962.6m, a 2% increase year-on-year, with international and direct-to-consumer (DTC) channels offsetting a decline in US wholesale revenue.
Sales in the US were impacted by later shipments of Fall 2026 wholesale orders, though these were partially offset by improved trends in DTC segments.
Gross margin in the quarter slipped 20 basis points to 49.8% due to support provided to factory partners, said the company. Operating income climbed to $109.6m, or 11.4% of net sales, compared to $67.4m, or 7.1%, a year earlier.
Columbia’s net income also rose to $84.7m, or $1.66 per diluted share, up from $52.0m, or $0.95 per diluted share, last year when performance was hampered by impairment charges.
The quarterly performance reflects early milestones in the company’s ACCELERATE Growth Strategy, which focuses on product innovation, digital enhancements, and expanding US DTC e-commerce to capture younger consumers.
Columbia chairman and chief executive officer Tim Boyle said: “We’re pleased to have delivered net sales and EPS growth exceeding our guidance for the third quarter. These results primarily reflected a portion of delayed Fall ’26 wholesale orders shipping earlier-than-expected, improved trends in our US DTC business, and the continued momentum of our international business, despite challenging global macroeconomic conditions.”
Columbia Sportswear nine-month performance
For the first nine months of the year, the company reported net sales of $2.36bn, a 1% increase over the prior year.
Gross margin increased by 220 basis points to 52.3% of net sales in the first nine months, up from 50.1% in the same period last year, largely due to a benefit of approximately 230 basis points from previously received IEEPA tariff refunds.
The company’s net income for this period was $145.6m, or $2.82 per diluted share, up from $84.1m, or $1.53 per diluted share, for the comparable period in 2025.
The effect of IEEPA tariff refunds, after allowances to factory partners, increased diluted earnings per share by $0.85.
Boyle added: “The operating environment remains challenging and uncertain, and we will continue working to elevate the Columbia brand and improve consumer perceptions in the US. That said, we are increasingly confident that the Columbia brand ACCELERATE Growth Strategy is gaining traction and putting us on the right track to return to healthy, sustainable growth over the longer term.”